

CareCredit Mobile
by Synchrony
4.2
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.2
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
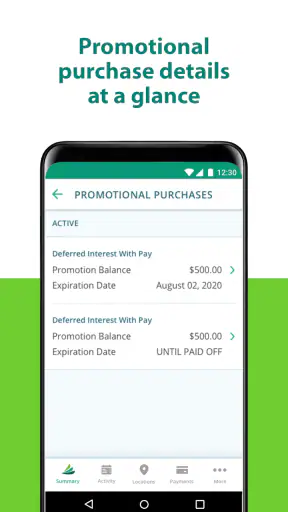
 Analysis by Getfullapps
When a medical, dental, vision, or veterinary bill arrives, the difficult part is often not only the amount due. It is remembering which account to use, finding the right payment details, and checking whether the transaction actually went through. CareCredit Mobile is built for that narrow but important moment: managing a CareCredit account from a phone instead of relying on a desktop browser or keeping a physical card nearby.
I found the app most useful when I treated it as a practical account-control tool rather than a general budgeting app. It is a free finance app from Synchrony, rated for Everyone, and its focus is clear: account management, payments, digital card access, and related tasks. That specialization is its main strength, but it also defines its limits. If you already use CareCredit and want faster access while away from a computer, it makes sense. If you want a complete view of all your finances, it is too narrow.
From an upcoming bill to a completed payment
I’ll start with the moment a CareCredit bill needs attention, because the app’s value is easiest to judge in a real payment routine. I’ll focus on how I would move from checking the account to taking action, while keeping the provider’s receipt and my own records in the loop. That practical sequence also sets up the next section’s closer look at account access.
The starting condition: a CareCredit account that needs attention
The most realistic use begins with a familiar situation. I might be leaving a provider’s office with a balance to handle, checking an existing promotional purchase, or simply trying to avoid missing an account task. In that situation, opening a mobile app is more convenient than searching through old emails or waiting until I am back at a laptop.
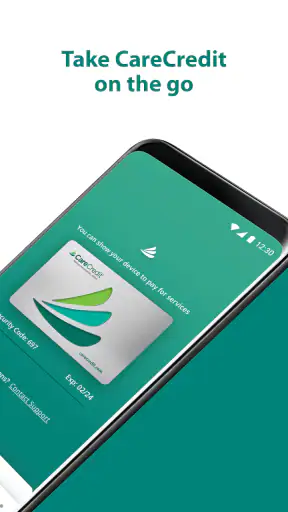
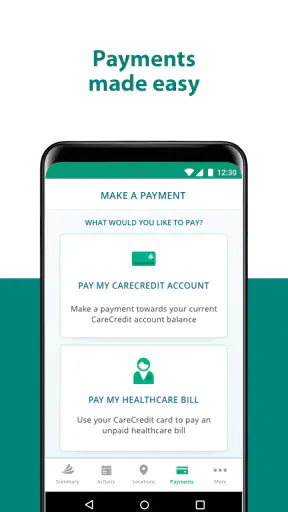
The app’s store summary points to the core workflow: manage the account, make payments, and use a digital card. That combination matters because the account and the card serve different moments. Account management is about reviewing and acting on the financing relationship, while the digital card is about having the payment credential available when I need it. Keeping both in one place reduces the need to switch between separate tools.
I also appreciate that the app does not pretend to be a general-purpose financial dashboard. CareCredit Mobile is designed around one account relationship. That makes the interface and purpose easier to understand than a broad banking app with checking, savings, transfers, investments, and credit products mixed together. The trade-off is obvious: its usefulness depends heavily on whether CareCredit is already part of my healthcare-payment routine.
Step one: getting into the right account
The first handoff is between me and my account. Before I can make a useful decision, I need to reach the correct CareCredit profile and understand what needs attention. This is where a finance app has to feel calm and deliberate. A payment account is not the place for confusing navigation, because a small mistake can create unnecessary worry.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
In everyday use, I would open the app before sitting down to pay, rather than waiting until the last possible moment. That gives me time to check the account context and confirm that I am acting on the intended balance. My practical tip is to make this a two-stage routine: review first, pay second. Separating those actions helps prevent the common mistake of rushing through a payment simply because the bill is in front of me.
The app is especially convenient for someone who handles healthcare expenses while traveling between appointments, work, and home. A phone-based account gives me a way to deal with the financial part of the visit while the details are still fresh. It also avoids depending on a paper card being in my wallet, provided the digital card is available for the situation.
Step two: checking the account before sending money
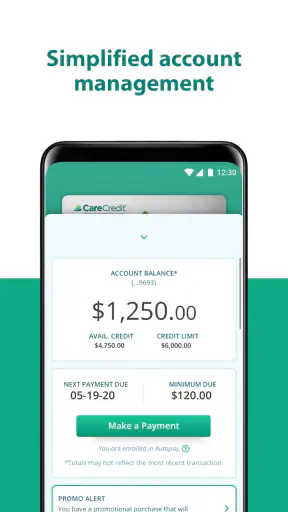
The most important part of a payment workflow is not tapping the final button. It is understanding what I am about to pay. I would use the account view as a checkpoint: confirm the account, review the amount or task in front of me, and only then move into the payment process.
This is one of the less obvious advantages of having a dedicated CareCredit app. A generic mobile wallet may help me pay at a terminal, but it does not replace the account-management step. Conversely, a bank app may show money leaving my checking account without giving me the same CareCredit-centered context. CareCredit Mobile sits between those two needs: it is not my bank, but it helps me manage the credit account that may be used for the healthcare purchase.
I would not use the app as my only record-keeping system. For a large medical expense, I would still keep the provider receipt and any payment confirmation with my household financial documents. The app can make the action easier, but good financial organization still benefits from an outside record. That is a workflow choice, not a criticism of the app; it is simply safer to keep evidence of important payments in more than one place.
Step three: making the payment
Once I have checked the account, the payment feature becomes the practical center of the experience. The benefit is convenience: I can handle the task from the same place where I reviewed the account instead of moving to a separate website or trying to remember another route.
I recommend slowing down at the final review. On a small screen, it is easy to confuse a payment amount, account selection, or confirmation step when I am multitasking. My preferred routine is to put the phone down for a moment after entering the details, read the screen again, and then submit. That small pause is more valuable than rushing for the sake of saving a few seconds.
After submitting, I would look for the app’s confirmation and keep a note of the transaction in my personal records. The handoff here is from the app back to my own financial routine. A successful tap is not the same as a completed household workflow; I still need to know what was paid, when it was paid, and whether the account now reflects the action as expected.
Step four: using the digital card when the physical card is inconvenient
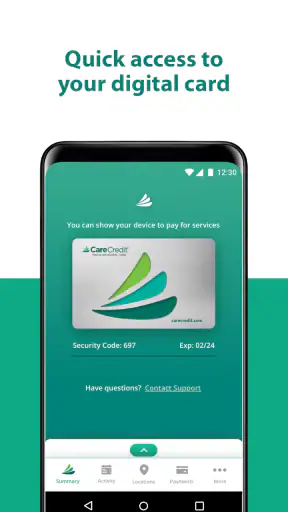
The digital card is useful in a different scenario. Imagine arriving at a participating provider and realizing the physical card is not in my wallet. Having access to a digital version can remove that awkward interruption and help me continue the checkout process from my phone.
This feature is most valuable when I prepare before the appointment rather than discovering the need at the counter. I would open the app in advance, make sure I can reach the digital card, and avoid turning a busy reception desk into a troubleshooting session. That preparation is a concrete advantage over treating the app as something I only open after a problem occurs.
There is also a trade-off. A digital card is convenient, but it makes my phone part of the payment handoff. If the battery is low, the device is unavailable, or the provider’s process does not suit the digital format, the convenience may disappear. I would still carry a backup plan for important appointments, especially when the purchase is time-sensitive.
The handoffs between the app, the provider, and my own records
CareCredit Mobile does not operate in isolation. A typical transaction involves at least three parties: me, the healthcare provider, and the CareCredit account. The app helps me manage my side, but it cannot replace the provider’s billing desk or my responsibility to verify the purchase details.
For example, the provider may explain the amount or financing arrangement, while the app gives me a place to manage the account afterward. Those are related but separate conversations. I would not assume that opening the app automatically resolves a discrepancy on a provider statement. If the amount looks wrong, the right move is to pause and clarify the bill rather than trying repeated payments.
The same applies to timing. A payment action inside the app belongs to the account workflow, while the provider’s receipt belongs to the care transaction. I would save both. This distinction is easy to overlook because everything happens around the same purchase, yet it can make a big difference when I later need to understand what was charged and what was paid.
Compared with paying through a desktop browser, the mobile app wins on access and immediacy. Compared with using only a digital wallet, it wins on account context. Compared with a traditional bank app, it offers a more focused route for CareCredit tasks. None of those alternatives is universally better; the best choice depends on whether I need account management, point-of-sale convenience, or broader money management.
The result: a shorter route to routine account tasks
When the workflow goes smoothly, the result is simple: I can move from an account question to an account action without leaving my phone. That is not a dramatic feature, but it is exactly the kind of convenience that helps with recurring financial chores. I do not need to postpone a payment-related task until I have access to a computer, and I can keep the digital card available for relevant situations.
The app’s public reception suggests that many people find this focused purpose worthwhile. It has an average rating of 4.2 from around 45 thousand ratings, with more than 1 million installs. I read those figures as evidence of broad practical use, not as a guarantee that every account experience will be frictionless. Finance apps are judged heavily by individual account situations, and a smooth interface cannot fix every issue connected with billing or credit management.
CareCredit Mobile is also free to download, which removes one barrier for existing account holders deciding whether a dedicated mobile tool is worth trying. The current version is 6.5.1, and the app requires iOS or Android 11 or later. That operating-system requirement is worth checking before planning to depend on it during an appointment. A phone that cannot run the app changes the whole workflow, particularly if I was expecting to use the digital card.
Where the flow breaks: account questions are not always app questions
The main limitation is specialization. The app can be a convenient front door to CareCredit, but it is not a replacement for every conversation I may need to have about a healthcare bill. If the issue concerns a provider’s charge, a disputed transaction, or confusion about the terms of a purchase, I should not expect a payment screen alone to explain the situation.
Another friction point is that mobile convenience can encourage rushed decisions. Because the app makes the account available almost anywhere, I may be tempted to pay while distracted, standing in a waiting room, or dealing with a family member’s appointment. My workaround is simple: use the app to access the account, but reserve the final review for a quiet moment whenever the amount is significant.
The app is also not the right choice for someone who wants one application to track checking accounts, credit cards from different issuers, savings goals, and household spending categories. A broader personal-finance app or a bank’s own application would be better suited to that job. CareCredit Mobile should be judged as a focused account companion, not as a replacement for a complete financial system.
People who rarely use CareCredit may also find the dedicated installation unnecessary. If I only need occasional access and am comfortable using a browser, the app may not add enough value to change my habits. Its strongest case is for regular users, people who want the digital card close at hand, and anyone who prefers handling account tasks immediately from a phone.
Who I would recommend it to
I would recommend CareCredit Mobile to an existing CareCredit customer who wants a direct way to manage the account during normal life: before an appointment, after receiving a statement, or when a payment needs attention away from a computer. The focused design makes more sense here than forcing every task through a general banking app.
I would be more cautious about recommending it as the only tool for managing a major healthcare expense. I would pair it with provider receipts, personal records, and a clear understanding of the purchase before making a payment. That approach preserves the app’s convenience without asking it to carry the entire administrative burden.
For families managing appointments for more than one person, the app can be useful as a quick access point, but organization matters. I would avoid making payment decisions from memory and would label saved records by patient, provider, and date in my own system. The app helps with the account action; it does not remove the need for careful household bookkeeping.
My final assessment after following the full workflow
CareCredit Mobile succeeds because it concentrates on a specific problem: giving CareCredit users a mobile route from account access to payment or digital-card use. I like that its value is easy to understand, and I find the phone-first workflow more practical than waiting for a desktop session when a healthcare expense needs attention.
Its weaknesses come from the same focus. It will not replace a bank app, a budgeting platform, or direct communication with a provider when the underlying bill is unclear. The digital card is helpful, but I would prepare it before an appointment and keep a backup plan. For payments, I would always review first, submit carefully, and retain my own confirmation record.
Developed by Synchrony, the app has been available since October 27, 2015, and its Everyone age rating makes it accessible to a broad audience. My recommendation is straightforward: if CareCredit is already part of your payment routine and your device meets the operating-system requirement, this free finance app is worth trying for the convenience alone. If you are looking for all-in-one money management, choose a broader tool and treat this as a specialized companion instead.
Pros
- Conveniently check your CareCredit balance and available credit on the go.
- Review recent transactions to monitor healthcare-related spending.
- Make payments directly from the app without visiting the website.
- Fingerprint or Face ID support can simplify account access on compatible devices.
- Useful reminders and account details help avoid missed payment deadlines.
Cons
- Some features may redirect you to a mobile website instead of staying in the app.
- Requires an active CareCredit account and reliable internet connection.
- Payment processing times may vary, especially around weekends and holidays.
- Users may need to update personal or security information through the website.
- Availability of features can differ depending on account type and device.
FAQs for CareCredit Mobile
What is CareCredit Mobile used for?
CareCredit Mobile is designed to help CareCredit cardholders manage healthcare financing from a smartphone. After signing in, users can generally review their account balance, check available credit, view recent transactions, make payments, and manage account details. It is intended for eligible CareCredit customers and may be useful when tracking purchases or planning payments for participating healthcare providers.
Can I make a CareCredit payment through the mobile app?
Yes, the app is intended to provide payment-management tools for eligible account holders. Depending on your account and the current app version, you may be able to make one-time payments, review scheduled or previous payments, and confirm payment information. Before submitting a payment, carefully check the amount, funding account, and due date, since processing times and available options can vary.
Is CareCredit Mobile secure to use?
CareCredit Mobile uses account sign-in and security features intended to protect personal, financial, and healthcare-related account information. You should download it only from the official Google Play Store or Apple App Store, keep your device and operating system updated, and avoid signing in over unsecured public networks. Never share your password, verification codes, or other authentication details.
Do I need a CareCredit account to use the application?
Most of the app’s account-management features require an active CareCredit account and valid sign-in credentials. If you are not already a cardholder, the application may provide information about applying or accessing CareCredit services, but availability can depend on your location and eligibility. Some features may also require identity verification or additional security steps during registration.
What should I do if CareCredit Mobile is not working or I cannot log in?
First, verify that your internet connection is stable and that you are using the latest version of the application. Recheck your login details, use the available password-recovery option, and restart the app if it becomes unresponsive. If the problem continues, contact CareCredit customer support through an official channel. Avoid repeatedly guessing passwords, as this could temporarily lock your account.

CareCredit Mobile
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via appsupport@synchronyfinancial.com, visit https://www.carecredit.com/, or review their https://www.carecredit.com/privacy/.










